JOURNAL / AI & PERSONAL FINANCE

Can you trust AI
with your money?

A chatbot can make a financial idea easier to understand. That does not make a plausible answer a suitable plan. Recent research finds potential in AI guidance, while showing how much depends on the question, the person, and the decision being made.

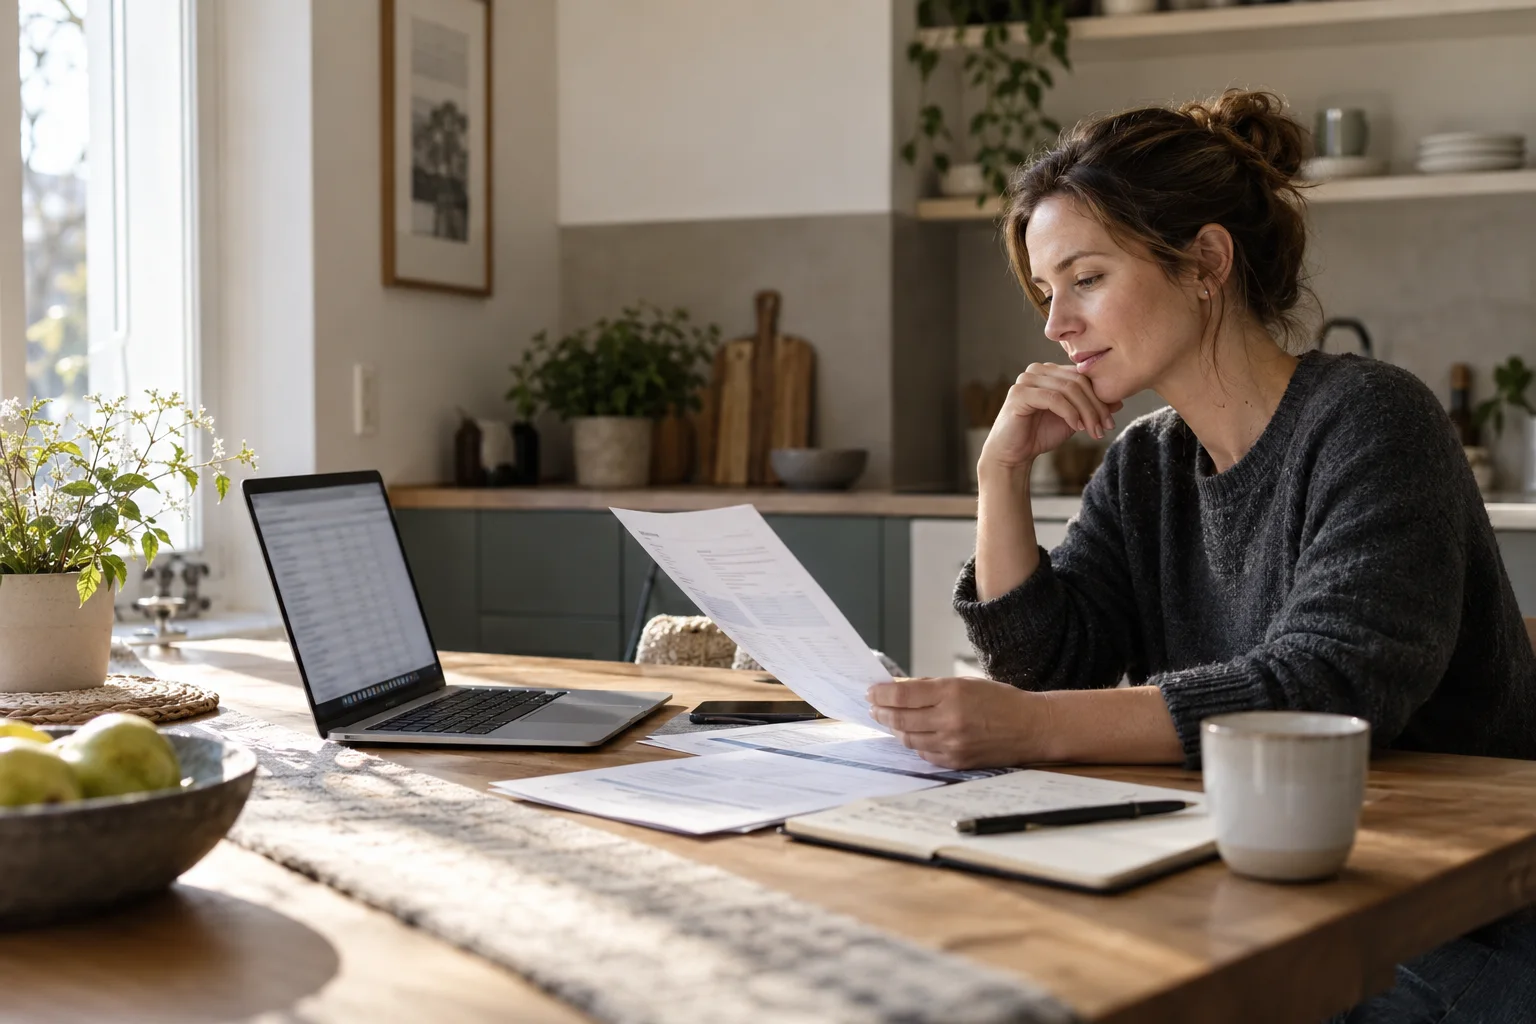
A woman reviews household financial paperwork and a blurred spreadsheet at a sunlit kitchen table.FINANCE / GUIDANCE / EVIDENCE / SYMPLOKA
A CLEAR EXPLANATION IS A STARTING POINT

Good questions make advice easier to examine.

A model can help organize options. A sound decision still depends on facts, trade-offs, and sources the answer may not know.

01 / DIFFERENT QUESTIONS, DIFFERENT STAKES

Financial help is more than one task.

Asking what an interest rate means is different from deciding where to put retirement savings. A model might explain a term, summarize a document, outline questions for an adviser, or compare options. Each step needs different information, and an answer that is useful for learning may be too incomplete for a personal decision.

The test is not whether the reply sounds confident. It is whether its assumptions fit the situation, whether its numbers can be checked, and what might happen if a key fact changes.

02 / WHAT THE 2026 STUDY TESTED

Promising advice, simulated consequences.

A 2026 MIT Sloan working paper asked 1,000 U.S. adults to write prompts seeking spending and investment guidance. The researchers gave those prompts to GPT-5.2 and Gemini 3 Flash, translated the responses into savings and portfolio choices, and simulated how those choices could play out over a lifetime under modeled income, job, and market conditions.

In the simulations, following the models’ advice generally moved people closer to standard life-cycle benchmarks: holding a savings buffer, participating in diversified equity funds, and reducing the share of stocks with age. The team also found that advice changed when prompts were written with more complete information about a person’s circumstances.

Those are modeled outcomes, not a trial showing that real users saved more or earned particular returns. The paper studies two named models at one point in time, and its results depend on its economic model and how written answers were translated into decisions.

Read the MIT Sloan working paper ↗
03 / THE PROMPT IS PART OF THE SYSTEM

Different questions can produce different futures.

The paper reports that guidance varied with characteristics including financial literacy and gender. In its simulations, these differences corresponded to a 4–5% gap in wealth at retirement. That is not an observed gap in real people’s bank accounts: it is the modeled effect of following different advice over a working life.

When the researchers separated the sources of one gender-related difference in investment advice, about two-thirds came from the prompts people wrote and about one-third from model responses changing when the same question was attributed to a different gender. This does not by itself establish why the differences occur or whether every difference is unfair. It does show why evaluations should test both the questions people bring and the answers a model returns to matched questions.

See the researchers’ summary and scope ↗
04 / WHEN THE INTERFACE MATTERS

A useful explanation is not the same as a good outcome.

In two 2025 pilots, the U.K. Financial Conduct Authority tested ways to simplify financial concepts and compared a fixed chatbot with a website question-and-answer format for cash-savings questions. Its research note found potential to make information more readable, but emphasized that comprehension and engagement depend on how the tool is designed and placed in a customer journey.

The pilots show why a model should be evaluated inside the experience people actually use, with human judgment as well as automated checks. They do not establish that every chatbot improves financial decisions, and the savings pilot is not a test of personalized investment recommendations.

These are U.K. and U.S. research and regulator examples. Financial products, rules, and protections differ by country; confirm local requirements and product terms before relying on them.

Read the FCA’s two-pilot research note ↗
05 / A PRACTICAL CHECK BEFORE YOU ACT

Make the answer show its working.

  1. Set the context: State the country, relevant date, and the decision you are trying to understand. Leave out names, account numbers, passwords, and other identifying details.
  2. Separate facts from assumptions: Ask which details came from your prompt, which were inferred, and what information is still missing.
  3. Ask for the source: Check that links lead to the named regulator, provider, or original document, and that the source supports the specific claim.
  4. Verify the numbers: Recalculate important figures independently and confirm rates, fees, eligibility, and deadlines against the current official terms.
  5. Compare scenarios: Ask what changes if income, costs, timing, or risk tolerance changes. A single answer can hide the trade-offs.
  6. Pause before transferring money: Independently find the organization’s contact details and verify registration where applicable. Regulators warn that scammers use AI claims and deepfakes to sell fake investments; guaranteed-return promises are a red flag.

AI can help turn a confusing question into a clearer one. The useful boundary is to let it explain and organize information while important decisions remain tied to verifiable facts, current terms, and accountable expertise.

Read the SEC, NASAA, and FINRA investor alert ↗
RESEARCH & PUBLIC GUIDANCEChoukhmane, de Silva, Lin & Akuzawa, AI Financial Advice: Supply, Demand, and Life Cycle Implications, MIT Sloan Working Paper 7377-26 (2026) ↗Financial Conduct Authority, Money Talks: Lessons from Two LLM Pilots on Consumer Guidance (2025) ↗SEC, NASAA & FINRA, Artificial Intelligence and Investment Fraud: Investor Alert (2024) ↗